The company is registered, the tax number has arrived, and you are ready to start invoicing. Then comes the question every foreign founder runs into: where will the money actually go? Every company in Montenegro needs a local business (giro) account to pay taxes, receive payments and run payroll.
The good news is that foreigners can open a business bank account in Montenegro without much trouble, provided the paperwork is in order. You need a registered company with a tax number, the founding documents, notarised signatures and identity papers for the people who represent the company. The bank will also check who owns the business, and in most cases it will want to meet the director at least once.
Key Takeaways
- A company must be registered and hold a tax number (PIB) before a Montenegrin bank will open its account.
- Banks work from an official document list, then add their own requests for foreign owners and directors.
- Every person who owns 25% or more of the company, or controls it in another way, will be identified.
- Foreign documents need an apostille and a translation by a court interpreter licensed in Montenegro.
- Most banks expect the director or an authorised signatory to visit a branch in person at least once.
- An open account brings ongoing duties, including employee registration and a yearly beneficial ownership check.
Register the Company in Montenegro First
A bank will not open an account for a company that is still being formed. The government’s business portal lists the registration decision and the tax registration decision (PIB) among the documents every bank requires, so the order is fixed: registration, tax number, then the bank.
Companies are currently formed under the Companies Act that took effect on January 1, 2026, and the Tax Administration’s company setup guide explains the tax side of incorporation.
If you want to skip the forms, VegaPlus handles legal structure selection (DOO, holding or branch), registration, the tax ID and VAT registration, and can also provide a registered business address.
Check the register before the bank does
The company register is kept by the Tax Administration on its IRMS portal, where the business entity search is public, free and needs no account. Banks compare your documents against that entry. A misspelled name or an outdated address in the register is enough to pause the process, so check it before your appointment.
Documents Montenegro Banks Require
The core list is short and set by the state. According to the official guide, a company submits the bank’s account request, the registration decision, a copy of the founding act, a deposit agreement and signature card signed at the bank, the OP form with notarised signatures of authorised representatives, ID copies of those persons and the PIB decision.
| Document | Issued by | What foreign founders should know |
| Account opening request | The bank | Filled in at the branch |
| Registration decision | Tax Administration (company register) | Must match the live register entry |
| Founding act | The founders | Foreign corporate founders add apostilled papers from home |
| Tax registration decision (PIB) | Tax Administration | Required before the account opens |
| OP form | Notary in Montenegro | Notarised signatures of company representatives |
| Signature card and deposit agreement | The bank | Signed in person at the branch |
| Identity documents | Authorised persons | Foreign directors present a passport |
Additional documents for foreign owners
Banks apply their own risk rules on top of the official list. Finance Plus reports that banks may ask foreign founders for proof of business activity, a CV or sample contracts, and Law & Trust adds proof of the owner’s financial standing and a reference from their current bank.
Prepare the following in advance:
- a short CV for the owner and the director
- a brief description of the planned business, with contracts or invoices if available
- a recent statement or reference letter from your home bank
- a politically exposed person (PEP) declaration
- proof of the source of the starting capital
Few banks ask for everything. Having it ready usually turns several visits into one.
Apostille and translation rules
Foreign documents must carry an apostille and then be translated by a sudski tumač, a court interpreter licensed in Montenegro. The apostille comes first, because the apostille itself has to be included in the translation. Some banks want each document apostilled separately and no older than three months. Ask your chosen bank for its exact list before you visit a notary at home.
Beneficial Ownership Checks in Montenegro
The bank needs the names of the real people behind the company, and it will not open the account without them.
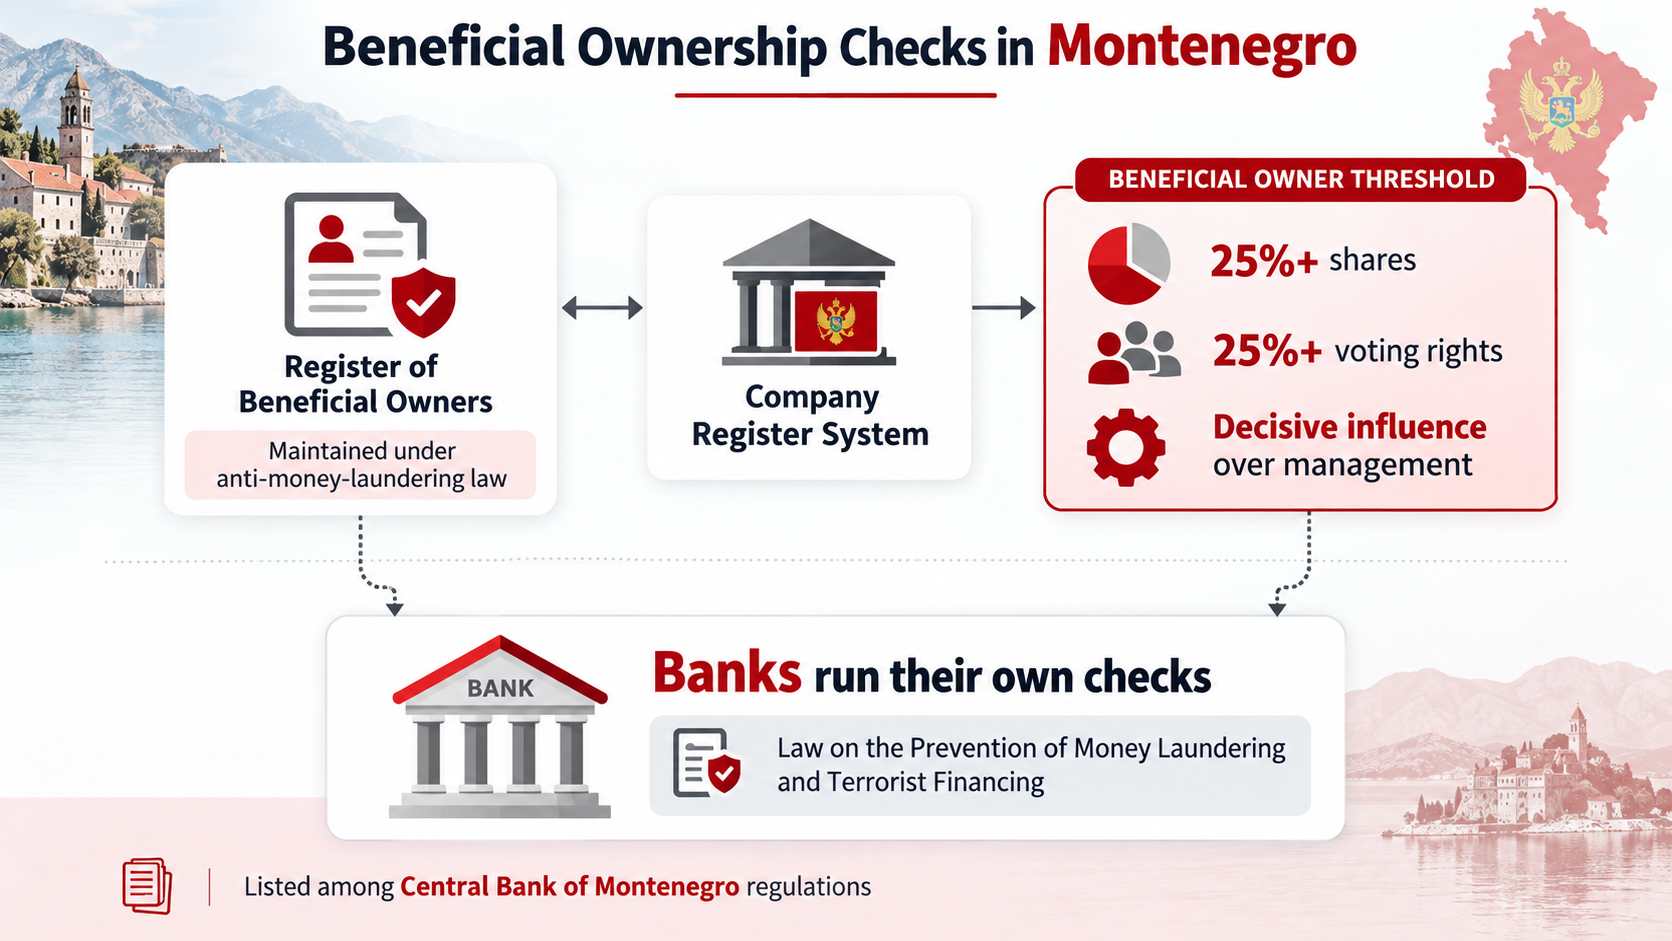
Montenegro keeps a Register of Beneficial Owners within the company register system, under the anti money laundering law, with a threshold of 25% of shares or voting rights, or decisive influence over management. Banks run their own checks as well, under the Law on the Prevention of Money Laundering and Terrorist Financing, listed among the Central Bank’s regulations.
How banks trace ownership
Imagine a Montenegrin DOO owned by a Cypriot holding, which is in turn owned by a German family company. The bank follows that chain until it reaches a person. Each layer means another company extract, another apostille and another translation. A simple ownership structure opens noticeably faster.
Annual confirmation
For new companies, the executive director registers the beneficial owners when obtaining the digital signature certificate, and the data must be confirmed or updated every year by March 31, with fines from €3,000 to €30,000 for failing to register. Banks compare their records with the register, so outdated data can block payments on an otherwise healthy account.
Foreign Directors and Branch Visits in Montenegro
Plan for at least one trip. Some banks work through representatives, but most want to see the director.
Eurofast states that physical presence is required and that opening takes about 14 days on average, depending on the bank, the applicant’s jurisdiction and document completeness. Other local advisors confirm that certain banks accept a notarised power of attorney instead, so policies differ from bank to bank.
What happens at the branch
The visit usually covers identity verification, signing the signature card and setting up online banking access. Book the notary appointment for the OP form on the same trip and one visit can close several tasks.
Opening through a power of attorney
A power of attorney must be notarised in the country where it is signed, apostilled there and then translated in Montenegro. Confirm with the bank that it accepts this route before you sign anything. If you also plan to live in the country, residence permits require personal presence for identification and biometrics regardless of any power of attorney. VegaPlus prepares and submits residence applications, including temporary, permanent and Digital Nomad permits.
Choosing a Bank in Montenegro
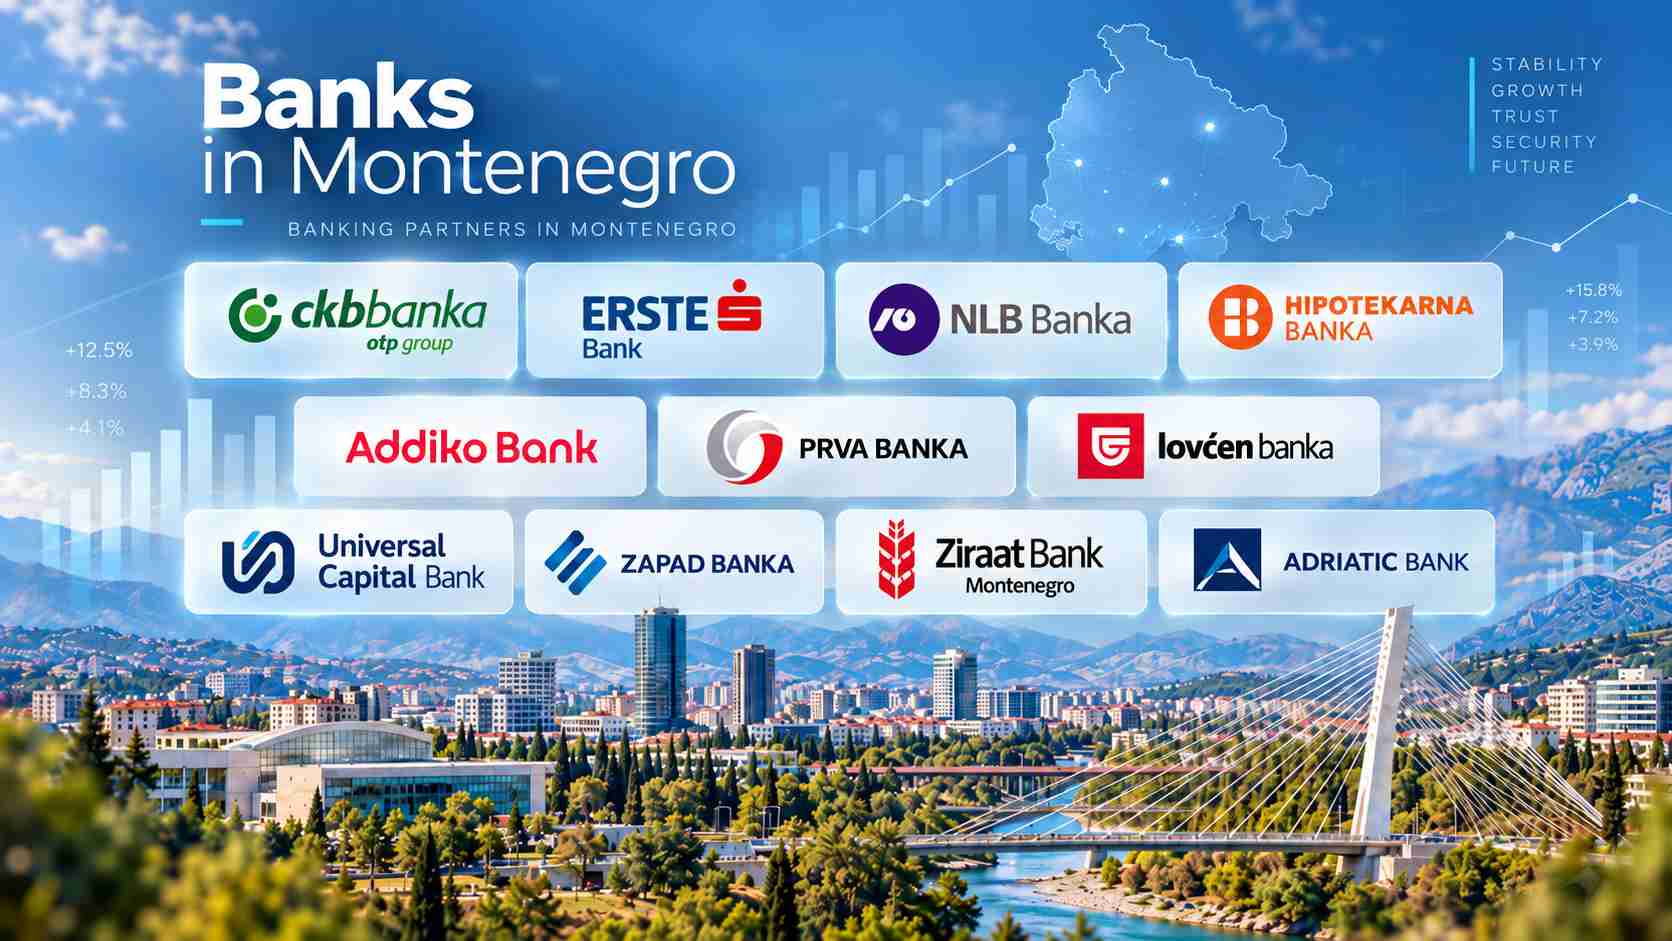
The Central Bank’s current list includes 11 banks, among them:
- CKB (part of OTP Group)
- ErsteNLB
- Hipotekarna
- Addiko
- Prva banka
- Lovćen
- Universal Capital
- Zapad, Ziraat
- Adriatic Bank
Montenegro uses the euro without being part of the eurozone, so your account runs in euros, with foreign currency accounts available alongside it.
When comparing banks, ask about English speaking staff, international transfer limits and how the bank views your industry. Timelines range from two to five business days with complete documentation, up to around two weeks. The difference almost always comes down to how complete your file is.
After the Account Opens
Once the account is active, several obligations start running:
- Activate online banking and collect your cards and security tokens.
- Register employees with the Tax Administration, including yourself if you are employed as director.
- Register for VAT if your turnover requires it, or voluntarily.
- Confirm your beneficial owners every year by March 31.
- Report any change of director, address or ownership to both the register and the bank.
New laws and amendments are published in the Official Gazette of Montenegro, and consolidated texts are available on me.propisi.net.
How VegaPlus Supports Foreign Founders
From the first incoming payment, every transaction on your new account becomes part of your company’s books. Bank statements need to be matched with invoices, salaries have to be calculated before contributions are paid, and monthly and annual reports follow fixed deadlines whether the company is busy or quiet.
Many founders underestimate this part and only look for an accountant when the first tax return is already due. Bringing an accountant in as soon as the account opens means your records are clean from day one, your payroll is correct from the first salary, and nothing in the register or at the bank falls out of date.
Most delays come from missing papers and banks that each want something slightly different. At VegaPlus, we cover the whole route: company registration and documentation, coordination with banks and authorities, tax ID and VAT registration, and post registration compliance guidance.
Once the account is running, the accounting team takes over bookkeeping, payroll and employee registration, monthly and annual reporting, and tax returns, while the tax advisory team helps with corporate and personal tax planning, dividends and VAT structuring.